An estate plan is a legal toolbox that helps you and your family if you cannot handle things on your own, and when you pass away. Once the plan is set up, here is what I show clients about how the estate will ultimately pass. In most cases your estate passes through two "funnels."
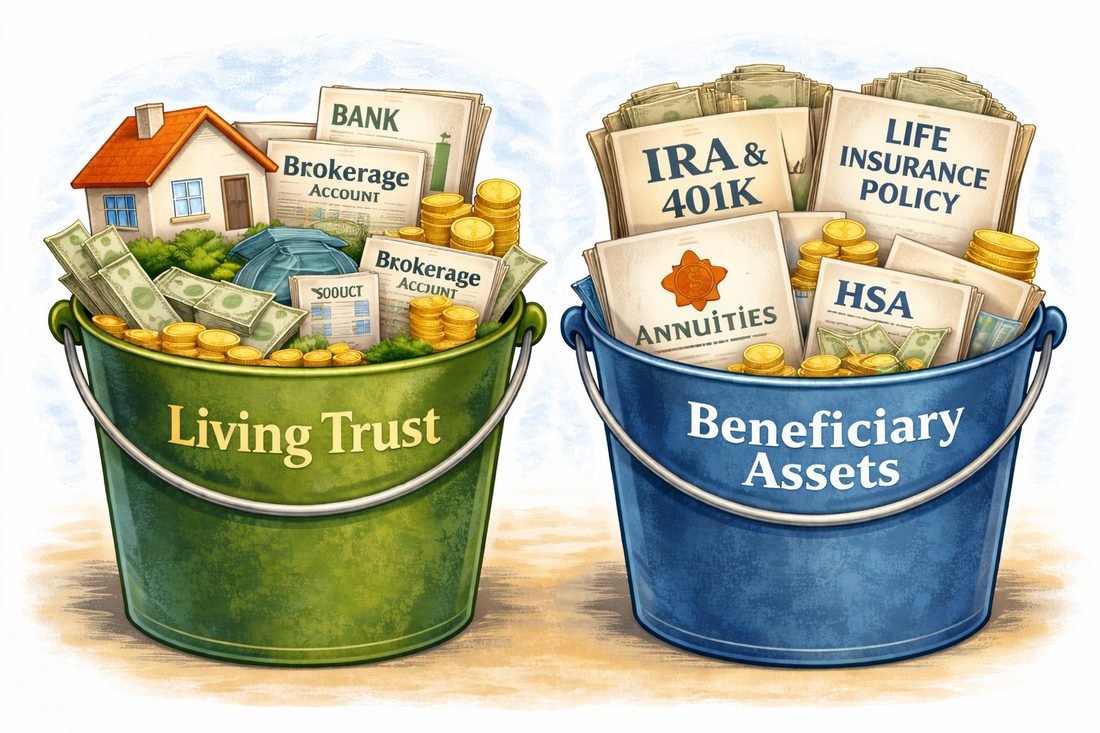
Funnel 1: the living trust
If your plan is like most, a living trust is one of the tools. Some of your assets pass through the living trust funnel. The assets in this funnel are titled in the name of your living trust. For example, your real estate would not be in your name or someone else's. If your name is Robert Smith, it would be titled in the "Robert Smith Living Trust."
The funnel also holds bank accounts, regular investment accounts, mutual funds, CDs (certificates of deposit), credit union accounts and savings bonds. Any basic kind of account goes here.
These assets ultimately pass to the people you designated as beneficiaries of your living trust. Sometimes they do not go to those people right away. Depending on how you set things up, they may stay in the trust for a period of time.
Funnel 2: the beneficiary funnel
This funnel typically holds tax-deferred and retirement accounts such as IRAs, 401(k)s and 403(b)s. Pension benefits may also pass by beneficiary, which means you have to contact the HR department where you work or used to work and ask who the beneficiary of your pension is. Annuities and life insurance also pass by beneficiary.
A few wrinkles
Joint ownership trumps both funnels.
As a general rule, assets owned jointly pass to the surviving owner and do not pass through either funnel. If you own an asset with Joe Smith and you pass away, Joe Smith gets it. It does not matter what your living trust or beneficiary designation says.
Assets in the trust funnel have three major benefits.
They avoid the court system, because anything in the name of your trust does not have to go through the courts when you pass away. They are managed by the people you chose as trustees. And they are governed by the rules of your living trust. Whoever manages them has to play by the rules you outlined, because the living trust is simply an enforceable legal document that says what happens to those assets.
Beneficiary designations trump your trust.
If you name Joe Smith and Sally Smith as beneficiaries, they get the asset. What you say in your trust or will is irrelevant to a beneficiary designation. The exception is naming your trust as the beneficiary.
Life insurance and retirement accounts
For life insurance you can name individuals, but I often like the beneficiary to be the trust. The proceeds then come through the beneficiary funnel and go directly into the living trust funnel. The money from the policy is payable to your living trust, which is the "beneficiary." That is sometimes a very good idea when you want the money to stay in the trust and be managed for your beneficiaries. It may or may not be right for you.
For retirement and other tax-deferred accounts, I generally like to name human beings. It is usually simpler administratively and has tax benefits and other advantages. Unless you have significant concerns about the people you are choosing, go ahead and name them. That is usually the best way.
Primary and secondary beneficiaries, with percentages
Name "primary" beneficiaries and also "secondary," sometimes called "contingent," beneficiaries. People often find that they do not have the correct beneficiary, do not have any beneficiaries, or have only a primary beneficiary such as a spouse and no one second in line.
You also have to state the percentages. If you have two children and want them to get equal shares, say "Equally to John Smith and Mary Smith," or "Equally to John and Mary Smith," or "50% to John Smith and 50% to Mary Smith." You need to be specific. People have run into trouble when they were not specific with their beneficiary designations.
If I can help with your estate plan, please contact my office at 661-414-7100 or visit www.mansourlaw.com.